Separate the backlog from today’s obligations
List ongoing bills separately from overdue amounts. This helps show what is needed to keep current services running and what needs a catch-up arrangement or further advice.
Gather the newest statements and notices first. An old balance may have changed through payments, fees, transfer or collection activity. Mark any figure that is not confirmed.
CFPB’s bill-planning guidance recommends considering consequences as well as dates. Do not let the oldest envelope automatically determine which issue receives attention first.
Identify anything that needs a prompt response
Look for court papers, a shutoff or eviction notice, a benefits deadline or a warning affecting necessary property. Record the exact date and contact the appropriate legal or assistance service.
A promise to make a payment may not stop an action already underway. Ask what formal arrangement or response is required and obtain confirmation.
If a deadline has passed, seek advice promptly with the actual document. Avoid assuming either that nothing can be done or that a late payment alone repairs the situation.
Verify accounts before negotiating
Ask the provider for a current account history and explanation of unclear charges. For collections, CFPB describes debt-validation and communication options.
Compare the response with receipts, statements and other records you have. Keep uncertain or disputed amounts separate from confirmed obligations.
For an old debt, get appropriate advice before payment or written acknowledgment. The FTC explains why old-debt rules can matter. A desire to put the past behind you should not force a rushed legal or financial decision.
Describe the current situation without overpromising
You can say, “I am reviewing overdue accounts and need to understand the balance and available options.” If relevant, explain that your circumstances have changed and give realistic information about what you can afford.
Ask about hardship assistance, fee review or repayment arrangements. Find out the total cost, future payment requirements and consequences if the arrangement is interrupted.
Request written terms. Do not agree to a payment based on income you hope to receive or sacrifice essential needs simply to demonstrate sincerity.
Keep several arrangements from colliding
Place proposed payments on one calendar with ordinary living costs. An individually manageable agreement can become unaffordable when combined with the others.
A qualified counselor can help review the full picture. Legal or tax obligations may also need specialist advice. Ask each adviser what their service covers rather than assuming one person handles every debt type.
Record which requests are pending, which agreements are confirmed and what still needs verification. Update the list when a response arrives.
Use the record to move forward
Keep payment confirmations and check that they are applied correctly. If circumstances change, contact the provider through the agreed route rather than waiting for several missed payments.
The purpose is a workable current arrangement, not a financial performance of remorse. Accurate information and realistic commitments are more useful than an explanation you feel pressured to repeat to every company.
About this guide
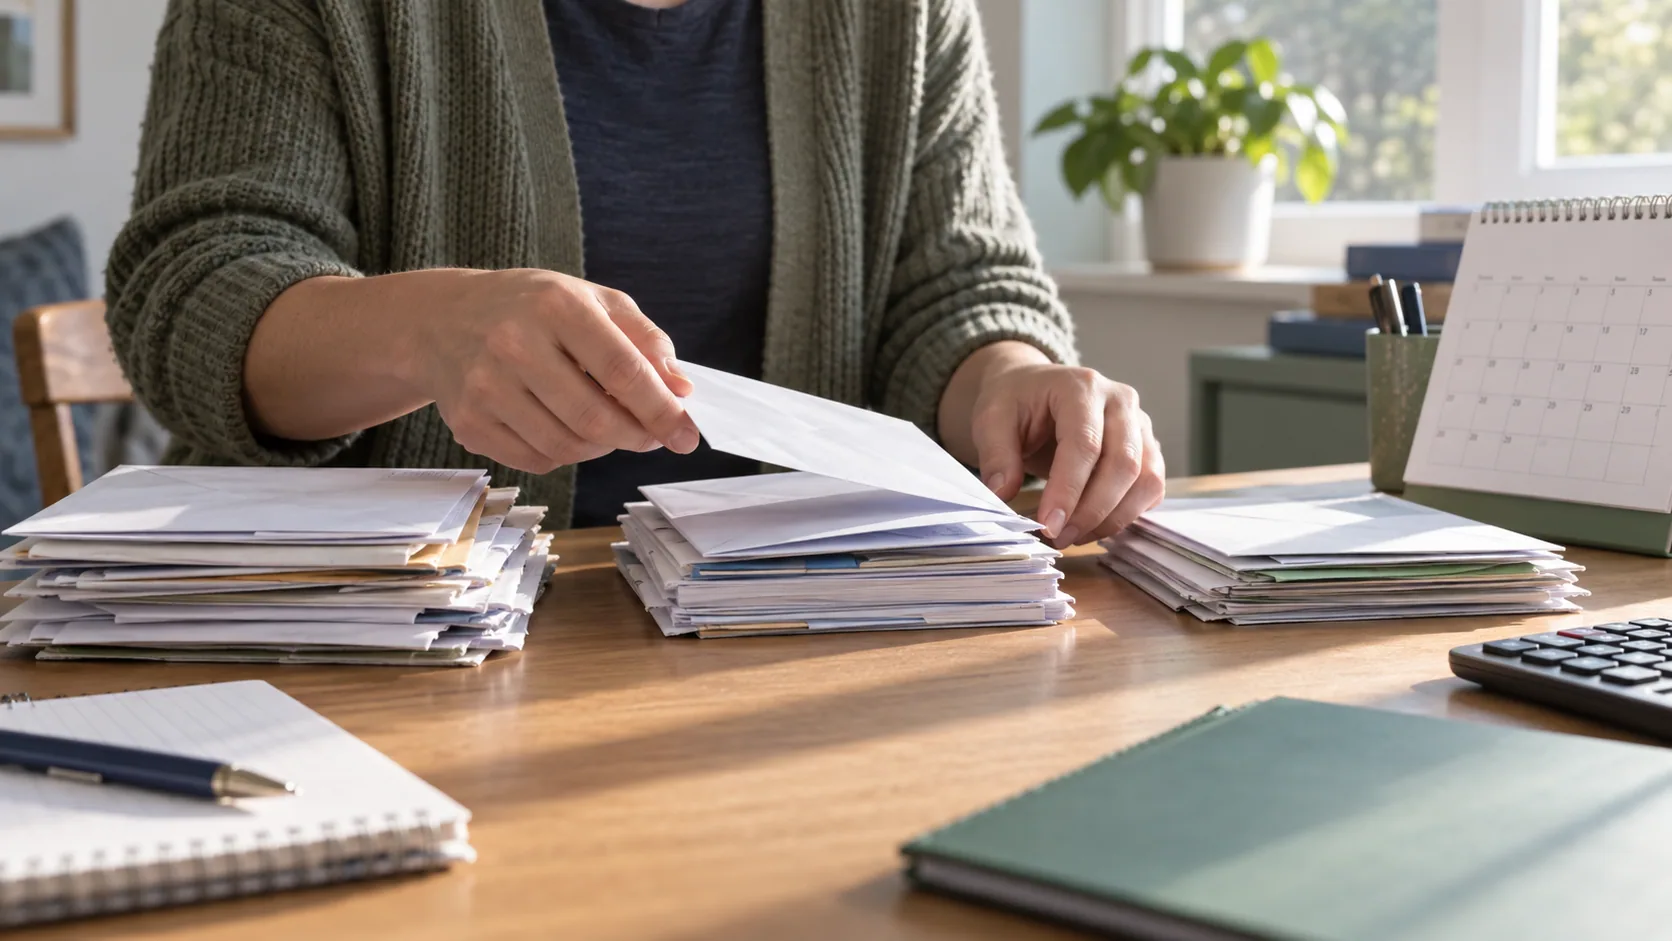
AI-generated editorial image; it does not depict a real person or event discussed in this guide.
Examples in this guide are illustrative, not reported experiences.
SoberSphere provides independent general information, not individual medical, legal or financial advice. No provider referral, affiliate arrangement or specialist review is claimed.